
Before a Black child earns a first paycheck, they should understand how money moves, how lenders measure risk, how contracts transfer power and why ownership outruns consumption.
BY SHABAZZ | KOURAGE & KULTURE
FOUR LAW FOCUS: TELL THE TRUTH • SUPPORT THE BUSINESS • PROTECT THE LEGACY
Too many children are taught to save money without being taught what money is supposed to accomplish. A jar can hold currency. A treasury gives currency instructions.
The family treasury is a living system of accounts, agreements, records, protections and assets. It teaches the child that every dollar must receive an assignment before emotion, advertising or outside pressure can claim it.
- Income feeds the present.
- Savings purchases time.
- Credit negotiates terms.
- Investment recruits money to produce more money.
- Ownership keeps the value inside the family.
A child trained only to earn can become a highly paid consumer. A child trained to allocate, verify, negotiate and acquire becomes difficult to exploit. The mission is not to raise children who merely possess money. The mission is to raise Black stewards who can direct resources, recognize traps and build structures that remain after they are gone.
Build a Five-Pocket Treasury
A child should be able to look at ten dollars and see five decisions—not one opportunity to spend. Create five labeled envelopes, jars or account categories and require every dollar received to pass through them.
- Protection: Cash reserved for emergencies so desperation does not dictate the family’s choices.
- Growth: Money placed into long-term assets that can increase in value.
- Enterprise: Capital for tools, training, inventory or a child’s first business.
- Circulation: Money deliberately directed toward Black-owned businesses, family responsibilities and community institutions.
- Living: Planned spending for enjoyment—without invading tomorrow.
The percentages can change as the child matures. The categories should remain. A dollar assigned to protection cannot quietly become entertainment. Enterprise money cannot disappear into impulse purchases. Moving funds between pockets requires a reason, a conversation and a record.
This practice develops more than budgeting. It trains restraint, foresight and command. The child learns that money is not merely something to possess—it is organized energy that must answer to a purpose.
Credit Is Rented Reputation
A credit score is not money, income or proof of wealth. It is a lender’s estimate of risk, calculated from information inside a credit report. It can help a family negotiate access and better terms, but it cannot replace cash reserves, productive assets or ownership.
Teach the machinery plainly. In the general FICO model, the score is influenced by:
- 35% — Payment history: Were obligations paid on time?
- 30% — Amounts owed: How much available credit is being used?
- 15% — Length of history: How long have the accounts existed?
- 10% — New credit: How aggressively is the person seeking new accounts?
- 10% — Credit mix: Has the person managed different forms of credit?
These percentages are general weights and may operate differently across individual credit profiles. The deeper lesson remains: reputation is built through repeated behavior, not tricks.
A valid FICO score generally requires at least one account open for six months and at least one account reported within the previous six months. This destroys the myth that a child automatically begins adulthood with a score. Credit must first be reported, aged and managed.
The Black family must teach credit as a tool—not an identity. Use it to reduce borrowing costs, secure productive property and negotiate from strength. Never worship the number. A high score can open a door, but only ownership determines what remains in the family after the debt is paid.
Protect the Name Before Building the File
A child’s identity is a financial asset before that child owns anything. Guard it.
Children under 18 generally should not have credit reports unless they are authorized users, joint account holders, victims of identity theft or connected to a reporting error.
Parents and guardians should:
- Check all three credit bureaus for unexpected files in the child’s name.
- Freeze the child’s credit where eligible to block fraudulent accounts.
- Secure Social Security numbers, birth certificates and account credentials.
- Investigate bills, collection calls or credit offers addressed to the child.
- Dispute false accounts immediately with the bureau and reporting company.
Do not wait until the child applies for an apartment, vehicle or business financing. Protect the name before the Nation’s youngest builders need to use it.
Authorized User Means Apprenticeship—Not a Shortcut
Adding a child as an authorized user can place account history on the child’s credit file—but only when the card issuer reports authorized users. It does not guarantee a score, approval or favorable terms.
Before connecting the child’s name:
- Confirm that the issuer reports authorized users to the credit bureaus.
- Use an established account with perfect payment history and controlled balances.
- Keep possession of the physical card until the child demonstrates discipline.
- Review the account every month with the child present.
- Remove the child immediately if the account becomes unstable.
The lesson is not “Here is credit.” The lesson is: “Here is how reputation is recorded, protected and leveraged.”
Never attach a child’s future to an adult account carrying chaos. Credit apprenticeship must transfer discipline—not damage.
Move the Child Up the Ownership Ladder
Consumption ends when the product is used. Ownership can continue producing value.
Move Black children through five levels:
- Own a tool: Equipment that develops skill or produces income.
- Own inventory: Products the child can price, market and sell.
- Own intellectual property: Writing, photography, music, designs or digital creations.
- Own financial assets: Age-appropriate, adult-supervised investments that introduce equity and long-term growth.
- Own productive property: Land, equipment, business interests or other assets capable of serving the family beyond one generation.
Do not begin with luxury. Begin with usefulness.
The first asset does not need to be expensive. It needs to teach the child one permanent truth: ownership changes their position from buyer to builder.
Read the Deal—Not the Payment
A low monthly payment can conceal a long, expensive obligation. Teach children to examine the entire agreement before admiring what it buys.
Before signing, identify:
- Cash price: What does it cost without financing?
- Amount financed: How much is actually being borrowed?
- APR: What do the interest and covered fees cost together?
- Term: How long will the obligation control future income?
- Total repayment: What will be paid from beginning to end?
- Add-ons and penalties: Which charges can be rejected or negotiated?
- Ownership conditions: Who controls the asset, and when does full ownership transfer?
If the seller keeps returning to the monthly payment, return to the total cost.
The signature is where emotion ends and obligation begins. Train Black children to slow the room down, read every line and ask the question pressure tries to silence.
Make the Child Keep the Books
Money without records becomes rumor.
Give the child a notebook or spreadsheet. Every transaction must show:
- Date
- Source of money
- Revenue received
- Expenses paid
- Profit remaining
- Treasury pocket selected
- Receipt or proof
- Current balance
Teach the equation early:
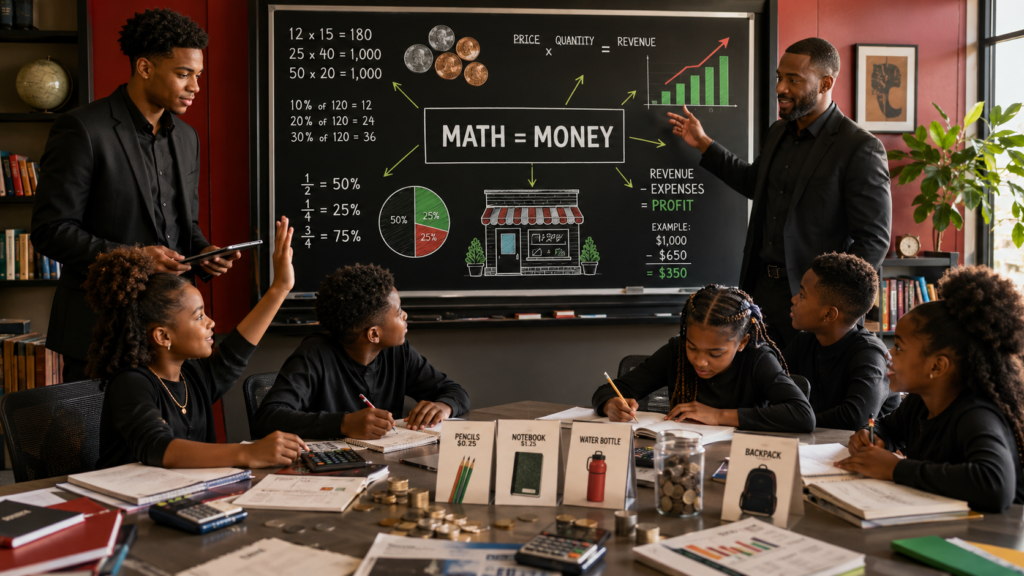
Revenue − Expenses = Profit
A child who sells $100 worth of products did not necessarily make $100. If supplies, transportation and fees cost $65, the profit is $35. Confusing sales with profit creates loud businesses with empty accounts.
The ledger forces truth. It reveals where money entered, where it escaped and whether the activity actually produced value.
The 30-Day Family Treasury Drill
Knowledge becomes power only after practice.
- Week One — Reveal: List family income streams, recurring expenses, debts, assets and financial documents.
- Week Two — Assign: Establish the child’s five treasury pockets and divide every gift, allowance or earned dollar.
- Week Three — Protect: Begin checking the child’s credit files, secure identity documents and request appropriate freezes.
- Week Four — Acquire: Help the child purchase or create one productive asset, then record every related cost and return.
At month’s end, the child delivers a five-minute treasury report:
- What entered?
- What left?
- What grew?
- What was protected?
- What will change next month?
Do not lecture children about money while hiding every family decision. Let them witness responsible planning, correction and growth. Participation produces judgment.
Leave Command—Not Confusion
A Nation cannot finance its future through financial confusion.
Do not leave Black children bills without instructions, property without records, businesses without books or names without protection. Give them the ability to measure value, question terms, control appetite and recognize the difference between looking prosperous and becoming powerful.
The child who learns to govern ten dollars can eventually govern ten thousand. The amount changes. The discipline remains.
The Four Laws Inside the Treasury
- Tell the Truth: State the real cost, debt, risk, revenue and profit.
- Respect the Builder: Compensate labor, credit creators and maintain what others sacrificed to establish.
- Support the Business: Circulate money deliberately through Black enterprises capable of serving the community.
- Protect the Legacy: Secure identities, titles, records, beneficiaries and succession instructions.
We are not preparing Black children merely to afford what others produce. We are preparing them to create value, negotiate from knowledge, own the machinery and finance the future of the Black Nation.
That is the family treasury.