
A Reentry Money Blueprint for Documents, Digital Tools, Income and Stability
4 Law Focus: Protect the Legacy
Coming home is freedom—but freedom without a financial plan can quickly become another kind of pressure.
Housing is waiting.
Transportation is waiting.
Bills are waiting.
Family responsibilities are waiting.
And in today’s world, even applying for work, opening accounts, receiving payments and managing important documents often requires digital access that someone may not have used in years.
For a returning citizen, the first financial goal does not have to be becoming wealthy overnight.
The first goal is stability.
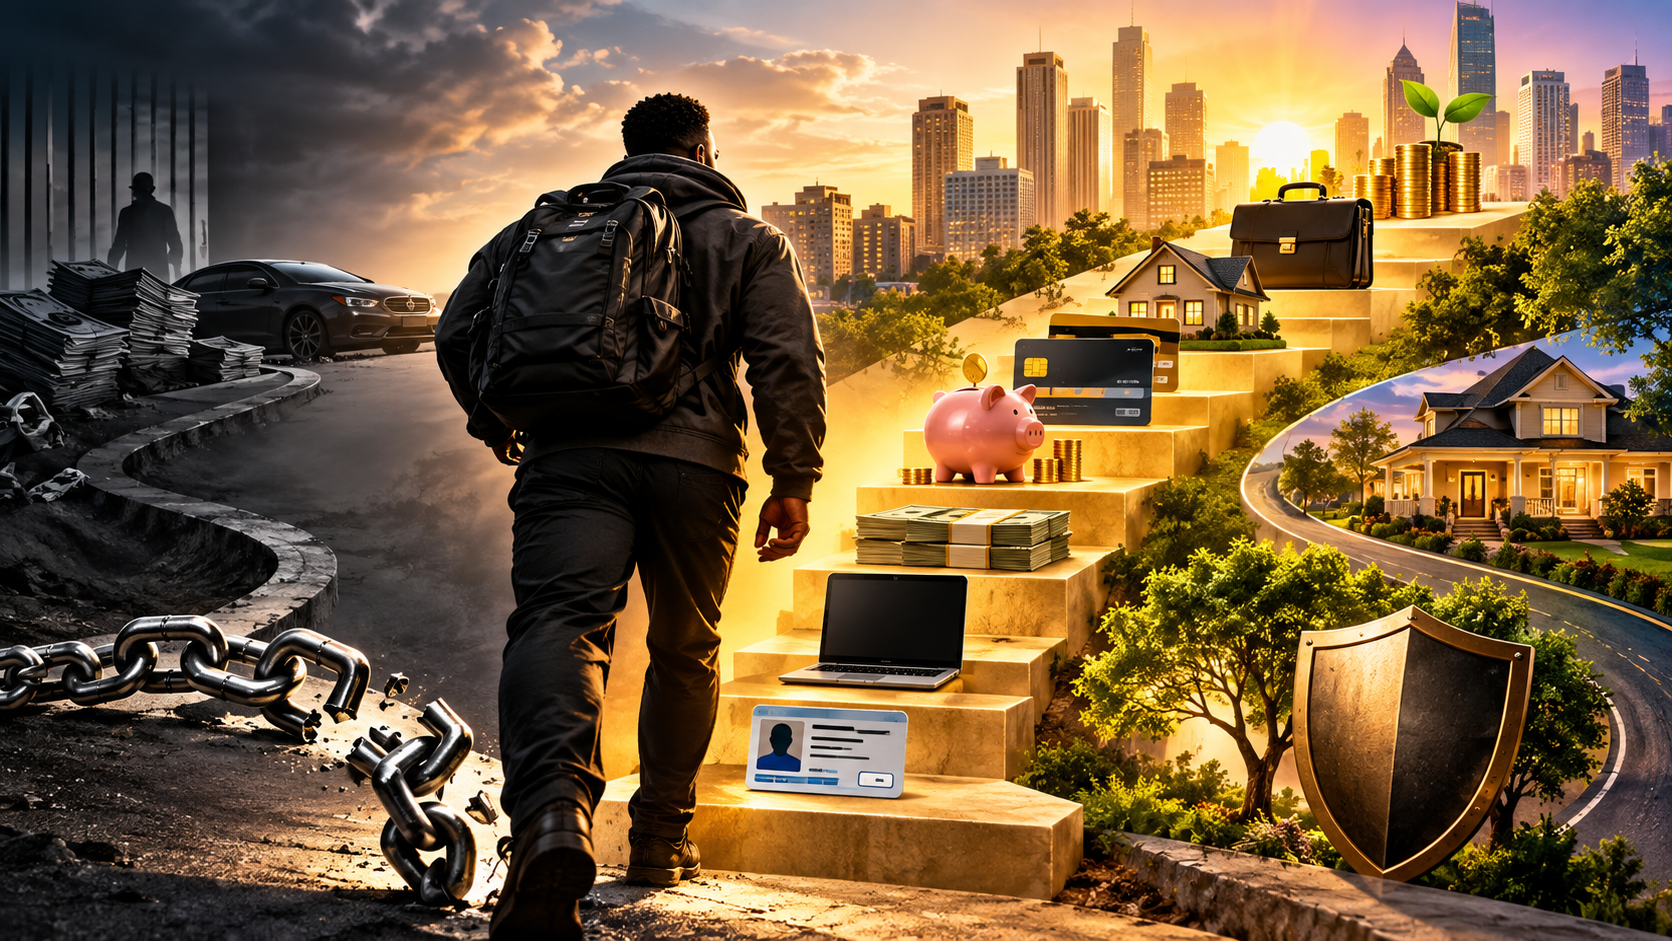
Get the documents.
Build the digital foundation.
Create legal income.
Control the money coming in.
Protect what you build.
Then begin turning survival into ownership.
Step One: Rebuild Your Financial Identity
Before credit, investing, business ownership or homeownership, a returning citizen needs access to the basic tools that make modern financial life possible.
That starts with identification and records.
A state ID or driver’s license.
A Social Security card.
A birth certificate.
Any release documents, employment records or benefit information that may be needed.
Without these, simple tasks can become major barriers.
Opening a bank account.
Starting a job.
Applying for housing.
Getting insurance.
Replacing a phone.
Setting up online financial accounts.
The goal is simple:
Get your identity documents organized before financial opportunities start showing up.
Keep physical copies in a safe place.
Create digital copies when possible.
Know where everything is.
Because financial stability becomes much harder when every opportunity starts with, “I can’t find the paperwork.”
Step Two: Build Your Digital Financial Foundation
Today, money moves through technology.
Direct deposit.
Banking apps.
Job applications.
Email.
Payment platforms.
Credit monitoring.
Online bills.
Tax documents.
For someone returning home after years away, the digital side of money can feel like another language.
So build it one piece at a time.
Start with a professional email address.
Use one phone number consistently.
Set up secure passwords.
Turn on two-factor authentication.
Create folders for employment, banking, taxes, identification and important documents.
Then learn the basic apps you will actually use.
The goal is not to download everything.
The goal is to create a system you understand and can control.
Digital access is now part of financial access.
If you cannot receive information, verify your identity, apply for opportunities or manage money online, you are starting every financial race several steps behind.
Step Three: Build Legal Income Before Chasing Big Money
When somebody comes home, the pressure to “catch up” can be intense.
That pressure can make fast money look more attractive than stable money.
But stability comes first.
Start with legal, dependable income.
A job.
A trade.
Contract work.
A service you can provide.
A small business that solves a real problem.
The first target is not image.
It is consistency.
Can you cover transportation?
Can you handle your phone bill?
Can you contribute to housing?
Can you save something every pay period?
Can you begin reducing old debt?
Can you build a record of dependable income?
Stable money creates options.
Once income becomes consistent, you can start thinking beyond survival and toward credit, savings, ownership and investment.
But the foundation has to be real.
Step Four: Give Every Dollar a Job
Once income starts coming in, the next move is control.
Not restriction.
Control.
Know what came in.
Know what went out.
Know what has to be paid first.
A simple starting structure is:
Housing. Transportation. Food. Phone. Debt. Savings.
Then build from there.
Even if the amount is small, start saving something consistently.
Five dollars.
Ten dollars.
Twenty dollars.
The habit matters before the amount does.
At the same time, watch the leaks.
Subscriptions.
Impulse spending.
Convenience purchases.
Fees.
Anything draining money without moving your life forward.
A budget is not punishment.
It is a map.
And when you are rebuilding after incarceration, knowing exactly where your money is going can mean the difference between constantly reacting and finally gaining control.
Step Five: Build an Emergency Buffer Before an Emergency Builds More Debt
One unexpected expense can knock a rebuilding plan off track fast.
A car repair.
A medical bill.
A missed workday.
A phone replacement.
A housing emergency.
Without savings, every problem can become new debt.
That is why one of the first financial goals should be a small emergency fund.
Do not wait until you can save thousands.
Start smaller.
Build the first $100.
Then $250.
Then $500.
Then keep going.
The purpose is not to impress anybody.
The purpose is to create breathing room.
When something goes wrong, you want options besides borrowing, overdrafting, using high-interest credit or falling behind on essential bills.
Emergency savings turns a crisis into a problem you can solve.
Step Six: Learn Your Credit Before You Use Your Credit
Credit can either become a tool or a trap.
The difference is understanding what you are dealing with before you start using it.
First, check what is actually on your credit reports.
Look for:
Collections.
Charge-offs.
Late payments.
Old addresses.
Accounts you do not recognize.
Balances that may be wrong.
Do not assume everything being reported is accurate.
And do not rush to open new credit just because somebody tells you it will “build your score.”
Understand the account first.
What is the interest rate?
Is there an annual fee?
When is the payment due?
How much of the limit are you using?
What happens if you miss a payment?
Credit is not extra income.
It is borrowed money that has to be managed.
Use credit to build access—not to finance a lifestyle you cannot afford.
Step Seven: Protect Yourself From Predatory Offers and Reentry Scams
Coming home can make a person a target.
Some businesses and individuals know that returning citizens may be under pressure for housing, transportation, credit, employment and fast cash.
That pressure can be exploited.
Be careful with:
High-fee loans.
“Guaranteed approval” offers.
Credit-repair promises that sound too good to be true.
Car deals built around desperation instead of affordability.
Business opportunities that require money upfront but provide no clear value.
Anyone asking for your Social Security number, banking information or passwords without a legitimate reason.
Do not let urgency make financial decisions for you.
Slow down.
Read the terms.
Ask questions.
Compare options.
Get a second opinion when necessary.
And never sign something you do not understand.
A bad financial decision made under pressure can follow you long after the pressure is gone.
Step Eight: Turn Income Into Ownership
The goal is not just to earn money.
The goal is to build something that lasts.
Once income becomes steady and the basics are under control, start thinking about ownership.
That may mean:
A reliable vehicle you can afford.
A business.
Tools for a trade.
A retirement account.
A home.
Investments.
Intellectual property.
Something that can grow in value or produce income over time.
Ownership does not happen all at once.
It happens in stages.
First stability.
Then savings.
Then stronger credit.
Then better access.
Then assets.
The key is to stop measuring progress only by what you can buy today.
Start asking:
What am I building that can still benefit me five, ten or twenty years from now?
That is where financial rebuilding starts becoming legacy building.
Step Nine: Protect the Legacy You Are Building
Making money is one thing.
Keeping what you build is another.
As your financial life gets stronger, protection has to become part of the plan.
That means keeping important documents organized.
Keeping beneficiaries updated.
Understanding insurance.
Protecting business records.
Protecting passwords and financial accounts.
Keeping taxes current.
And making sure the people you trust know where important information is located if something happens to you.
For families rebuilding after incarceration, this matters even more.
Too much progress can be lost when there is no plan for protection.
The goal is not just to get ahead.
The goal is to make sure what you build does not disappear because nobody prepared for the unexpected.
Protect the income. Protect the assets. Protect the information. Protect the legacy.
The Kourage & Kulture Reentry Money Blueprint
Coming home is not the end of the journey.
It is the beginning of rebuilding.
The financial order matters:
Identity first.
Digital access next.
Legal income.
A working budget.
Emergency savings.
Credit knowledge.
Protection from predatory offers.
Ownership.
Legacy protection.
None of these steps has to happen overnight.
The goal is progress with structure.
For returning citizens, financial stability is bigger than an individual bank account.
It can strengthen families.
Reduce pressure.
Create options.
Support children.
Build businesses.
Protect future generations.
And help turn a second chance into something sustainable.
The objective is not simply to come home.
The objective is to come home with a financial map—and build from there.
Kourage & Kulture
Reclaim the Narrative. Build the Future.
kourageandkulture.com
news@kourageandkulture.com